If you’re trying to figure out whether in-home ABA therapy fits your family’s budget, you’re not alone. For many parents, cost is one of the first questions that comes up, and one of the hardest to pin down.
In many cases, in-home ABA is billed at about $120 to $250 per hour. But that number does not tell you what your family will actually pay. Your real cost can look very different depending on approved hours, deductibles, coinsurance, provider structure, and where you live.
This guide is here to make that picture a little clearer. We’ll walk through what affects the cost of in-home ABA, how insurance and Medicaid can change the math, and which questions can help you plan the next step with more confidence.
Quick Summary
- The cost of in-home ABA depends on more than one hourly rate.
- Weekly hours, insurance design, and the mix of providers involved often matter most.
- Some families pay the full billed cost, while others pay only part of it after coverage is applied.
- Younger children, school-age children, and teens may be recommended for very different therapy schedules.
- A written breakdown of hours, supervision, and benefits can make the decision feel much more manageable.
Quick Answer: What In-Home ABA Therapy Usually Costs
In-home ABA therapy is often billed in the range of $120 to $250 per hour. Total cost can vary widely because some children need focused, lower-intensity support while others may be recommended for a more frequent schedule. That means monthly costs may range from a few thousand dollars to much more before insurance is applied.
The most important thing to understand is the difference between billed cost and family-paid cost. A family with strong in-network benefits may owe only part of the total after a deductible, copay, or coinsurance. A family using private pay or out-of-network care may face a much larger direct expense.
There is no one standard number of hours that fits every child. A toddler starting early intervention may be recommended for a different schedule than an older child or teen working on more targeted goals. If you want a broader look at how benefits and out-of-pocket responsibility work, this guide to ABA therapy insurance coverage is a helpful place to start.
Why In-Home ABA Costs Vary So Much
Two families can hear the same hourly range and still end up with very different real costs. One major reason is therapy intensity. More weekly hours raise the billed total, but more hours are not automatically better. The right schedule should reflect medical necessity, day-to-day needs, and what feels sustainable for the child and family.
The provider mix matters too. A plan may include direct therapy with an RBT or similar therapist, BCBA oversight, caregiver training, and periodic reassessments. Each of those pieces can affect what is billed and what insurance covers.
In-home care also comes with practical logistics. Scheduling around school, work, sibling routines, and therapist travel can shape how services are delivered. For some families, home-based care feels more convenient and less disruptive overall. For others, it still takes real planning to make the schedule work.
Age can influence the plan as well. Younger children may need more caregiver coaching and early-intervention pacing, while older children and teens may need support tied to communication, independence, safety, or school routines. If you want a closer look at expenses that are easy to miss, this overview of hidden out-of-pocket ABA costs may help.
The HEART Cost Map for In-Home ABA
If the numbers feel overwhelming, it can help to slow the decision down. The HEART Cost Map is a simple way to think through affordability without losing sight of what your child and family actually need.
H: Hours That Match Real Need
Hours have a big effect on cost, so it helps to understand why a certain schedule is being recommended. Families deserve more than a number on a page. They need to know what those hours are meant to support and how the plan connects to real-life goals.
Early-intervention families may hear different recommendations than families seeking targeted support for an older child or teen. What matters most is that the schedule is individualized, not based only on budget pressure or a generic template.
E: Eligibility and Insurance Rules
Private insurance, Medicaid, and state-supported pathways all work differently. And “covered” does not always mean “fully paid for.” Families may still need to account for deductibles, copays, coinsurance, prior authorization, or limits on approved hours.
It helps to ask for benefit details in writing before services begin. Questions about network status, reauthorization, caregiver training, and reassessments are worth asking early. For a deeper explanation, this ABA insurance benefits overview can add useful context.
A: At-Home Logistics
In-home ABA can be a strong fit because it happens where daily life already unfolds. Skills can be practiced in the child’s natural environment, and families may avoid some of the travel and disruption that comes with clinic-based scheduling.
Even so, home-based care still requires coordination. Caregiver availability, therapist travel, home routines, and the time of day can all affect how smooth the plan feels. The home setting can reduce stress, but it does not remove the need for thoughtful scheduling.
R: Real Out-of-Pocket Spend
The billed rate is only part of the story. What families actually owe may depend on how much of the deductible has been met, whether coinsurance applies, and whether any parts of the plan are not fully covered.
It also helps to ask how billing may change if approved hours change. A plan can look very different financially when authorizations are adjusted, reassessments are needed, or parent training is covered differently from direct therapy.
T: Tradeoffs and Next Steps
Once the cost picture is clearer, the goal is not to rush. It is to make a grounded next decision. That may mean verifying benefits, comparing providers, asking for a written cost breakdown, or deciding what level of care feels sustainable right now.
If you want a hand talking through options and next steps, you can start with Alight ABA’s contact page.
What Families May Pay With Insurance, Medicaid, or Private Pay
The same in-home ABA plan can feel very different depending on how it is funded. That is why it helps to look at cost through the lens of real family responsibility, not just the provider’s rate sheet.
Private Pay
Private-pay families usually carry the highest direct cost because they are responsible for the full billed amount unless reimbursement is available. That can make it especially important to ask for a detailed breakdown of therapy hours, supervision, reassessments, and any other charges that may show up over time.
Insured and In-Network
In-network insurance may lower the direct cost substantially, but families can still face deductibles, copays, coinsurance, and changes tied to authorizations. In some cases, the most stressful part is not the sticker price. It is the uncertainty around what will actually be approved and what the monthly total will look like after benefits are applied.
If the insurance side feels confusing, this article on common ABA coverage application mistakes can help you prepare better questions.
Medicaid or State-Supported Coverage
Medicaid or state-supported options may lower direct family cost, sometimes significantly. But access can still depend on eligibility, provider availability, and paperwork requirements. Families may also notice that coverage pathways differ by state.
For example, families exploring services in Minnesota or North Carolina may run into different coverage rules, processes, or service-area realities.
Monthly and Annual Budget Scenarios Families Can Use
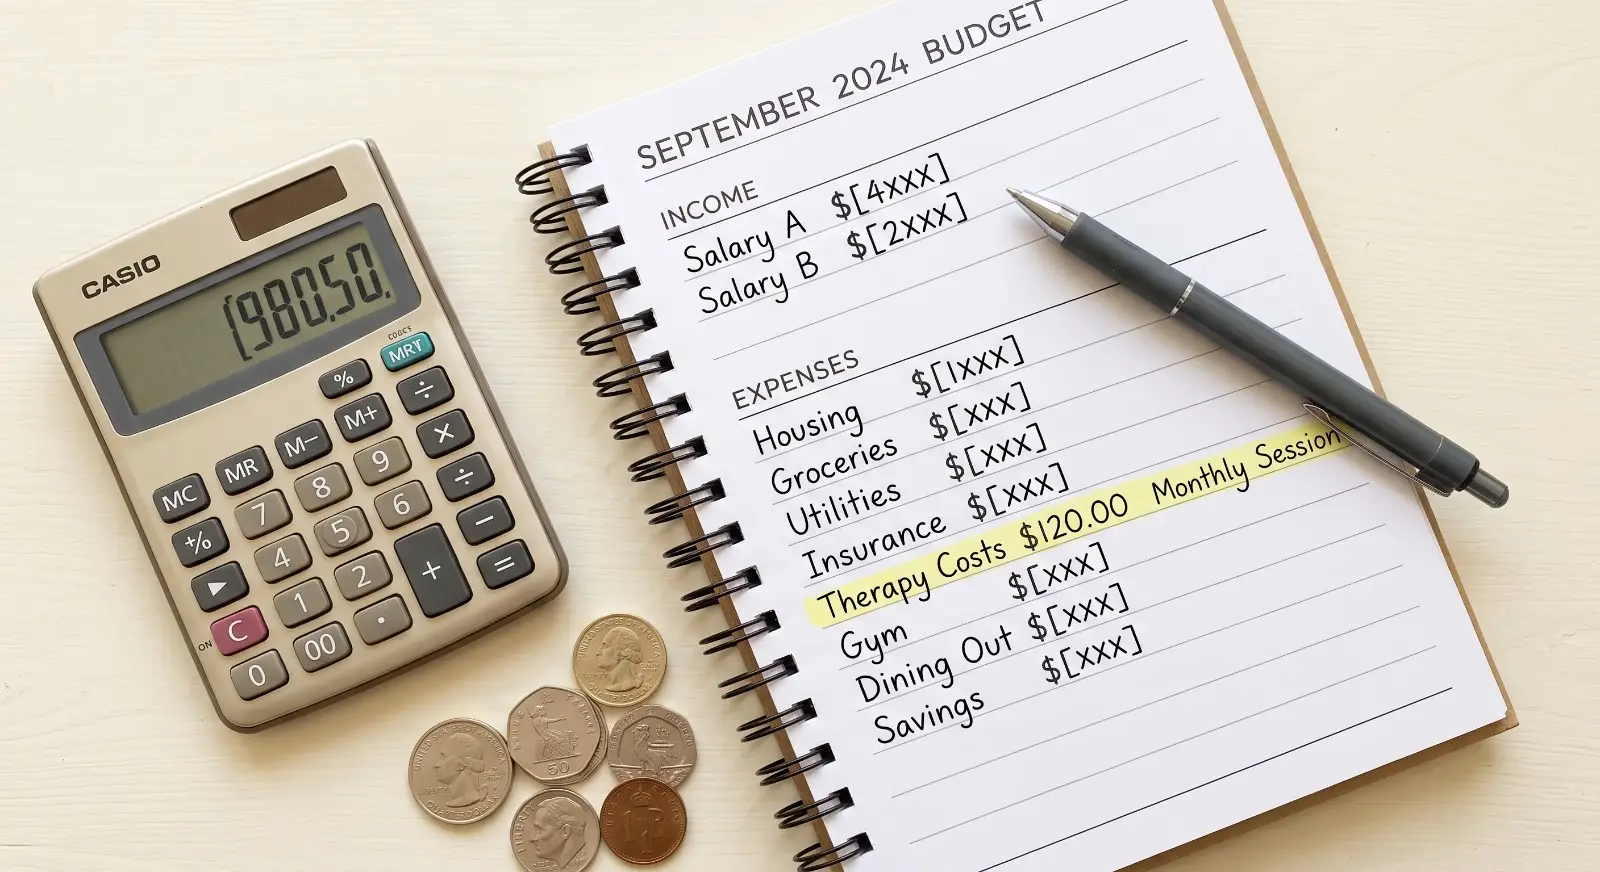
Budget scenarios are not quotes, and they are not clinical recommendations. They are simply a way to test what different levels of care might mean for your family financially before services begin.
Low Scenario
A lower-intensity plan may involve fewer therapy hours and more focused goals. In some cases, that may fit a school-age child or teen who needs support in a smaller number of areas.
Mid Scenario
A mid-range plan often includes steady weekly therapy, BCBA oversight, and caregiver training. This is where benefit details matter a great deal because insurance may cover a meaningful portion while still leaving a monthly out-of-pocket share.
High Scenario
A higher-intensity plan may be more common for some younger children with broader support needs. In those situations, billed totals can rise quickly, so it helps to ask three separate questions: what is clinically recommended, what is actually approved, and what feels sustainable for your family.
If the emotional side of affordability feels heavy, this piece on how middle-class families think about ABA costs may feel relatable.
Questions to Ask Before You Start In-Home ABA
When you are already juggling a lot, clear questions can make the process feel less overwhelming. Before services begin, it helps to ask for as much clarity in writing as possible.
- How many hours are being recommended, and what is that recommendation based on?
- How much direct therapy versus BCBA supervision is included?
- Is the provider in network with our plan?
- Does the plan require prior authorization or reauthorization?
- Are parent training and reassessments covered?
- What will our deductible, copay, or coinsurance responsibility be?
- What happens if fewer hours are approved than recommended?
- Are there missed-session policies or other charges we should know about?
If you are also comparing providers, this parent’s guide to choosing an ABA provider can help you think through the decision.
In-Home ABA Cost Planning Worksheet
An In-Home ABA Cost Planning Worksheet can make the numbers easier to compare side by side. It can include:
- private pay
- insured and in-network care
- Medicaid or state-supported care
- hours per week
- clinician mix
- deductible, copay, and coinsurance
- authorization and reauthorization details
- parent training and reassessment coverage
- hidden or secondary costs
- provider questions
- low, mid, and high monthly estimates
A simple worksheet like this can help families compare options before they commit and feel more prepared for follow-up conversations.
FAQ: Common Questions About In-Home ABA Costs
How much does in-home ABA therapy cost per hour?
In-home ABA is often billed in a rough range of $120 to $250 per hour, but the hourly rate alone does not show what your family will actually pay.
Is in-home ABA therapy covered by insurance?
Many plans do cover ABA therapy, but direct family cost still depends on benefit design, network status, and authorization rules.
What makes in-home ABA more expensive or less expensive?
The biggest drivers are weekly hours, provider mix, home scheduling logistics, location, and the details of your insurance coverage.
How much might a family pay each month after insurance?
There is no single number. Monthly cost depends on deductible status, coinsurance, approved hours, and whether every part of the plan is covered the same way.
Is in-home ABA more expensive than clinic-based ABA?
Sometimes it can be, but not always. In-home care has its own logistics, while clinic-based care comes with a different set of operating costs and family routines.
What should parents ask an ABA provider about cost before starting?
Ask about recommended hours, benefit verification, in-network status, provider mix, billing cadence, reassessments, and what happens if authorizations change.
For many families, the cost of in-home ABA feels a little less overwhelming once the right questions are on the table. If you want support understanding your options, Alight ABA offers a next step here.